

Internal Control · 2025
In this section10 topics
- Internal Control — Board Opinion1 item
- Adequacy & Appropriateness of the Internal Control System2 items
- Internal Control Deficiencies3 items
- Audit Committee & Auditor Observations2 items
- Opinion on the Head of Internal Audit2 items
- Appointment, Discharge & Transfer of the Head of Internal Audit2 items
- Related Party Transactions1 item
- Counterparties & Transactions3 items
- Policy & Future Trends2 items
- Appraised Assets & Appraisal Prices1 item
Internal Control — Board Opinion
Summary of the Board's Opinion on Internal Control
The Company has implemented governance to operate within the framework of a publicly listed company with acknowledgement and highlights the significance of management oversight and corporate governance, aligning with best practices in governance, which includes a commitment to sustainability practices.
The Board of Directors of the Company appointed the Audit Committee to oversee the internal control systems, corporate governance and provide advice on the management of risks under responsibility of the Risk Management Committee as well as the Company management and executives to ensure an adequate, appropriate and effective internal control system. In addition, responsibilities include supervision of the Company’s compliance with relevant laws and regulations, ensuring no conflict of interest, monitoring connected transactions, proper care and use of resources. Also, oversight mechanisms are designed to prevent or root out corruption or misbehavior where checks and balances and wider accountability mechanisms are available. The Audit Committee agreed to hire an external consultant: a professional with expertise that is hired to review the internal control systems of the Company's key operational processes to be in line with Best Practice. Beneficially, the Company could bring helpful and useful expertise in striving to obtain a progressively better internal control system.
Adequacy & Appropriateness of the Internal Control System
Introduction
The company has evaluated its internal control system to ensure it is adequate and effective in managing operations in line with goals, objectives, laws, and relevant regulations. This system effectively prevents asset fraud and damage, and ensures accurate and reliable financial reporting. The company uses an internal control adequacy assessment form (“Assessment Form”) developed in accordance with the guidelines of the Securities and Exchange Commission (SEC), with the assistance of PwC Thailand. The Audit Committee has recommended that the company's management participate in evaluating the adequacy of internal controls using this form, which is based on the COSO (Committee of Sponsoring Organizations of the Treadway Commission) framework.
The Company has an internal control process that is systematically established as the organizational procedures for all operators to implement cooperatively in order to assure that given method or operational practice are reasonably efficient to achieve the objectives of the Company internal control system.
1. Separation of duties: by differentiating and separating duties such as different requestors to different approvers, different payee to different account controller and different sellers to different inventory clerk, etc.
2. Authorization: Proper authorization practice is the key for internal audit control system.Requiring specific individuals to authorize certain types of transactions provides internal record that an activity has been seen, reviewed, and approved by appropriate authority before it can be processed or paid.
3. Documentation: Documentation is a crucial component to maintaining internal controls. They provide an internal record for what actions need to take place, by whom, and in what order they should be taken, ensuring consistency in the completeness and accuracy of activities.
4. Reviewed, confirmed and reconciled: A reconciliation is performed after the business activity has occurred as a control that can detect errors or malfunctions that may occur in a timely manner.
5. Monitoring: Monitoring is carried out to ensure that the specified control processes are carried out truthfully and continuously.
The Company's internal control system procedures are provided by means of documenting and written manual as per below elements.
Organization Chart and the assignment of duties and responsibilities by setting up an appropriate organizational structure along with each of a reporting line to clarify delegating and assigning to responsible persons clearly. There is a specification of high-risk positions and periodic evaluation of sufficiency of the internal control system by the executives, the management department, the audit committee. and Board of Directors
Approval Framework appropriately delegates approval authorization especially for significant transaction by identifyingpersonnel along with the position and authorization scope to approve including transaction limit as a whole framework of authorization.
An operational manual shall be provided to each department which states regulations, guidelines and procedures under the same standard in order to analyze and evaluate or set the check point together.
For the evaluation and monitoring of the Company internal control system, the Audit Committee is responsible for selecting internal control system auditors and risks assessors. In the past years, the internal control system auditors were the internal auditor team from the group of shareholders, Carmeuse Coordinate Center, Internal Audit Group , of the Carmeuse Group, one of the world's largest lime producers with over 160 years of experience in the lime industry who also had a team of internal auditors with specific experiences in lime industry.Otherwise, the Audit Committee was to select local independent expert in the internal control system audit likewise to the past 5 years such as Grant Thornton Specialist Advisory Services Co., Ltd. (Y2023), KPMG Phoomchai Business Adviser Co., Ltd., Multiplus Audit and Consulting Co., Ltd., etc.
Internal Control Framework Used
| Framework | Detail |
|---|---|
| The Committee of Sponsoring Organizations of the Treadway Commission (COSO) | This framework includes an evaluation process covering 5 key components and 17 principles. 1) Control Environment Principle 1: The organization demonstrates its commitment to the value of integrity and ethics. Principle 2: The board of directors is independent from the management and has the duty to oversee and develop internal control. Principle 3: The Management, under the Board of Directors’ oversight, sets suitable reporting function as well as defining the commanding authorities and responsibilities so that the organization would achieve its goals. Principle 4: The organization displays its commitment to motivate, develop and maintain capable personnel Principle 5: The organization appoints personnel to have duty and responsibilities on internal control in order to achieve organizational goals. 2) Risk Assessment Principle 6: The organization clearly defines its objectives so that risks related to the achievement of such objectives can be identified and evaluated. Principle 7: The organization identifies and analyzes all risks that may affect the achievement of the organizational objectives. Principle 8: The organization considers the chance of fraud while assessing risks that may affect the achievement of organizational objectives. Principle 9: The organization is able to identify and evaluate changes that could affect the internal control system. 3) Control Activities Principle 10: The organization has control policy which would mitigate risks that would affect the achievement of organizational objectives to an acceptable level. Principle 11: The organization uses technology to select and develop general control activities in order to support its objectives. Principle 12: The Company sets up control activities trough policy which specified its expectation and practice procedure so that the policy can be put to practice 4) Information & Communication Principle 13: The organization has related and quality information to support the goal for internal control. Principle 14: The organization communicates information within the organization including the purpose and the responsibility for necessary internal control system so that the internal control could be conducted as planned. Principle 15: The organization has communicated with external agencies regarding the issues that may affect its internal control. 5) Monitoring Activities Principle 16: The organization monitors and assesses its internal control to ensure that the internal control is thoroughly and appropriately conducted. Principle 17: The Organization timely evaluates and communicates the internal control system flaws to responsible persons including high-level executives and board of directors as appropriated. The Audit Committee and the Board of Directors, at the meetings on February 24, 2026, reviewed the company's internal control system. This review, based on the internal auditor’s report and management's responsibility, involved seven top executives evaluating the internal control system for 2025. The assessment covered transactions with major stakeholders and confirmed adequacy across five components and 17 principles. Results were reported to the Audit Committee on February 24, 2026, concluding the company’s internal controls are sufficient and appropriate. Internal Controls audit results The annual internal audit performed by auditors appointed by the Audit Committee did not identify any high-risk issues, and recommendations to enhance internal control processes have been duly followed up and addressed by the relevant management teams. Nonetheless, a review of the internal control monitoring report presented to the Audit Committee indicated the presence of some recurring issues that remain unresolved within the responsible departments, notably those pertaining to IT infrastructure investments that entail substantial capital expenditure. General issues unrelated to capital expenditure have been addressed. On November 13, 2025, the Audit Committee presented its findings to the Board of Directors. Management committed to implementing KPIs to resolve the identified issues, particularly those related to IT infrastructure investments. The majority of observations have already been addressed promptly. The board of directors viewed that the company's internal control system is both sufficient and suitable, given its risk profile and within acceptable limits. The Audit Committee met on February 24, 2026, and the Board of Directors met on February 26, 2026; both meetings reviewed and agreed that the internal control system is adequate and appropriate for the year 2025 encompassing transactions involving major shareholders, Directors, Executives, or related parties, the Company has established internal control systems categorized into five distinct areas. These systems are designed to effectively safeguard assets against misuse or unauthorized access by executives. Furthermore, the internal control framework has been validated through an independent audit and assessment of the internal control system. The Company also maintains an efficient document management system, ensuring that Directors, auditors, and legal authorities can conveniently request document reviews within a reasonable timeframe. |
| COSO - Enterprise Risk Management Framework (ERM) | The COSO 2017 framework highlights the interconnectedness of strategy with an organization's mission, vision, and core values. It establishes a link between strategic and business objectives and associated risks, allowing organizations to implement comprehensive enterprise-wide risk management aimed at enhancing value creation. This framework can be delineated through three primary components: 1. Mission, Vision, and Core Values - Mission: The essential purpose of the organization, exemplified by SUTHA's commitment to sustainability and delivering maximum value. - Vision: The aspirational goals of the organization, such as SUTHA's aim to become a leading lime manufacturer in Southeast Asia. - Core Values: The distinctive norms and characteristics that shape the organization’s culture and influence behavior, including a focus on customer service and accountability. 2. Enterprise Risk Management in Relation to Strategy - Strategy encompasses the plans and actions necessary to achieve objectives, which are aligned with the mission, vision, core values, and acceptable levels of risk. The integration of risk management into strategic planning facilitates informed decision-making and optimal resource allocation. 3. Performance Enhancement - Performance pertains to the attainment of strategic and business objectives. It includes the assessment of financial returns, operational efficiency, governance, safety, and project results. A thorough understanding of the interplay between risk and performance is crucial for effective risk management. |
Internal Control Deficiencies
Introduction
The Company places importance and value on an appropriate and adequate internal control system, believing it can better the operational effectiveness. The Company has prepared comprehensive operational policy, regulations, and procedures. Furthermore, the separation of powers approach has been also set in accordance with check and balance principles. In addition, the Company regularly improves the business operating process in all departments as per suggestions from the internal control auditors.
Core operations that are subjected to random evaluation and internal control audit conducted by the auditors and internal control system auditors are as follows;
|
|
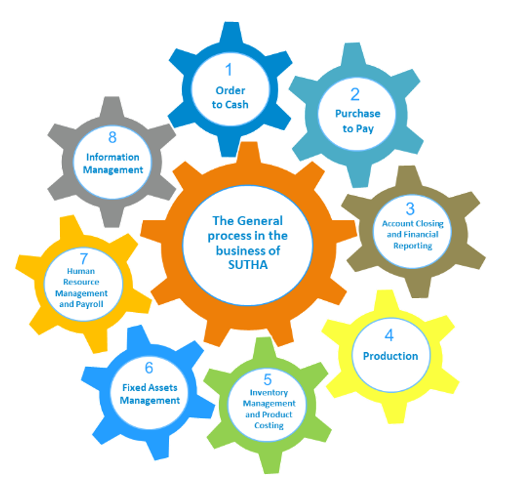
To indicate the results of the internal control system monitoring, the eOne Report Data Platform disclosure format specifies the identification of the number of deficiencies. The company has prepared a summary report of the audit results for the years 2023 to 2025, with the following details:
Number of Deficiencies
| Metric | Current Year | Previous Year | Two Years Ago |
|---|---|---|---|
| Total number of internal control system deficiencies (cases) | 1 | 1 | 1 |
Deficiency Details
| Period Type | Start Period (YYYY-MM) | End Period (YYYY-MM) | Detail | Progress Status | Corrective Action |
|---|---|---|---|---|---|
| Within (month/year) | 2025-12 | 2025-12 |
Summary of results from the internal control system audit for the year 2025/(1)
The internal auditors appointed by the Audit Committee meeting are:
Audit Team :Reanda Thailand
The audit team consisted of:
Team Leader: Surapol Thawalyawichit
Audit Team Member: Pathumporn Chalad
Duration:
- Location: Thai Marble Corportaion Ltd.
- Audit Period: 1 January 1 – September 30
Systems Audited:
(1) Revenue and Payment System
- Verification of policy/operational manual availability
- Assessment of the adequacy of internal control systems
- Verification of compliance with regulations
(2) Asset System (Tangible/Intangible Assets)
- Verification of asset investment policy
- Verification of purchase requests, approvals, and operations according to manuals
- Assessment of the appropriateness of investment and maintenance budgets
| Incident no longer subject to action | Findings and corrections: Six findings were identified as medium risk due to their impact on transaction accuracy, documentation, and controls. None of these issues affected organizational policy, so they were not classified as high risk. The company continues to monitor its internal control systems through audits conducted by internal auditors appointed by the Audit Committee. The audit results have been presented to relevant departments and sections, and key issues and actions are currently being followed up on by management. Overall, the audit results will be presented to the Audit Committee annually as per the plan, ensuring that processes are improved to meet good internal control standards. |
| Within (month/year) | 2023-12 | 2023-12 |
From the annual audit, minor deficiencies related to internal control were found as follows:
Summary of Internal Control System Evaluation for the Year 2023/(1)
Appointed Auditors:
Grant Thornton Specialist Advisory Services Co., Ltd.
Team Leader: Mr. Sittichai Chusupanasorn
Audit Team: Ms. Rachaneekorn Ngernmuang
Audit Scope:
- Duration: August 21, 2023, to September 22, 2023
- Location: Chongsarika Branch Factory and Production Processes
- Data Period: January 1, 2023, to July 31, 2023
- Systems Audited: Inventory management, production planning, quality control, production cost recording | Incident no longer subject to action | Findings (Low Risk) and Corrections: 1. Inventory and Quality Control: - Improved backup power for weighing card system - Enhanced chemical and physical quality inspection forms for limestone - Recorded physical inspection results from Thai Marble Company Limited - Established forms for meeting records and weekly production plans 2. Production Planning Process: - Improved production plan documentation to be non-editable - Created work schedules for weighing operators - Standardized limestone testing forms across branches for consistency and traceability Management has addressed these issues accordingly. |
| Within (month/year) | 2024-12 | 2024-12 | Appointed Auditors:
- Group Internal Audit Directors of Carmeuse
- Team Leader: Ms. Cathy Cully
- Audit Team: Mr. Mustafa Esat
Audit Scope:
- Duration: April 2024
- Locations: Three production plants (Chongsarika, Phra Phutthabat, Huai Pa Wai) and Khao Khao Mine
- Data Period: January 1, 2023, to February 29, 2024
- Systems Audited: Finance, human resources, logistics, IT, health and safety, sales and payment
| Incident no longer subject to action | Findings and Corrections:
|
Audit Committee & Auditor Observations
Audit Committee's Opinion Differs from the Board's
No
Auditor Has Observations on Internal Control
No
Opinion on the Head of Internal Audit
Head of Internal Audit
3160
Audit Committee's Opinion on the Head of Internal Audit
The selectively internal control system auditors, in the past years, the audit committee provided opinions on the selection criterion of qualified internal auditors from either a local proficient professional audit company that provides audit services for internal control systems or an international internal control system audit team appointed by the main shareholder that is a world-class company operating the same business which normally sends a team to audit the internal control system of the affiliated companies every 3 years.
The internal control system audit team from the major shareholders possess direct experience in internal control system auditing of the same business. The external independent audit team to conduct the internal control system audit would be under the consideration and selection of the Audit Committee to select a proficient experienced external audit team who, as an outsider, can provide constructively independent opinions towards the internal control system.
Appointment, Discharge & Transfer of the Head of Internal Audit
Requires Audit Committee Approval
Yes
Description
The Audit Committee is responsible for considering the appointment, transfer and termination of the chief of the internal auditor team or any other departments responsible for the internal control system audit under the scope of duties prescribed in the Audit Committee Charter approved by the Board. Each year, the Audit Committee will select the external audit firms as the Company’s internal auditor.
The Audit committee meeting No. 2/2025 on May 8th 2025 resolved to appoint Inter Audit from Carmeuse Group (Group Internal Audit Directors of Carmeuse) to be the internal control system auditor for the year2025
Internal Auditor Leader
Ms. Cathy Cully,
Group Internal Audit Directors of Carmeuse
Education:
1985-1989 Master of Business Administration (MBA), Accounting
1981-1985 Bachelor of Business Administration (BBA) Economics & Finance
CPA (Jan 2012-Dec 2014)
Experience:
North America Internal Audit Director
The internal control system of Thai Marble Corporation Limited (a subsidiary) was audited by an internal control audit team appointed by the Audit Committee meeting, consisting of Mr. Suraphon Thawanvitchachit and Ms. Pathumphon Chalad, internal control auditors from Reanda Multiplus (Thailand) (“IA Reanda”) The IA team presented a summary report of the internal control system review to the Audit Committee meeting on May 8, 2025, following their examination of the subsidiary’s internal control system.
Additionally, to facilitate coordination among the external audit team, with internal personnel available to provide support on related matters, the Audit Committee Meeting No. 4/2568, held on November 12, 2568, appointed and assigned internal executives to serve as coordinators for the internal control system. The individuals responsible for these positions include:
The Accounting and Finance Executive and/or
The Financial Control, Planning and Analysis Manager and/or
The person responsible for the duties of the Audit Committee Secretary.
The person responsible for the above-mentioned positions shall coordinate internal controls as follows:
The following are the duties and responsibilities:
1. Coordination with Internal Auditors
Coordinate with internal audit teams from the CarmeuseGroup and independent audit firmsapproved by the Audit Committee.
Support the development of internal control plans, risk assessments, and audit follow-ups.
Select executives to complete the annual internal control adequacy assessment.
2. Promotion and Development of Internal Control Systems
Work with the Human Resources Department to arrange training sessions and share information about internal control systems.
Encourage and support a culture of strong internal controls across the organization.
Take part in assessing and enhancing internal control systems so they fit the organization's needs.
3. Selection of Internal Control Auditors
Propose independent audit firms for annual appointments by the Audit Committee.
Select independent firms with no affiliation with the company or its major shareholders for appointments every three years or as deemed appropriate by the Audit Committee.
4. Handling Complaints and Whistleblower Reports
Receive complaints and coordinate with internal auditors in accordance with the company’s anti-corruption and whistleblower policies.
List of the head of internal audit or outsourced internal auditor
General Information | Telephone number | |
| cathy.cully@carmeuse.com | 412.995.5555 (USA) |
| surapon@reanda-th.co.th | 02 5400182-3 |
| paturmporn@reanda-th.co.th | 02 5400182-3 |
Related Party Transactions
Has Related Party Transactions
Yes
Counterparties & Transactions
Monetary Unit
1000000
Counterparties with Potential Conflicts
| Name | Person / Juristic Person | Type of Business | Nature of Relationship | As of Date (YYYY-MM-DD) |
|---|---|---|---|---|
| Thai Marble Corp., Ltd. (Subsidiary Company) (“TMC”) | Juristic Person | Marble Product, Lime Stone and GCC | Sales of goods / purchase product and raw material, transportation service, other service and inter-co loan
- There are common directors / Executives Necessity entering a connected transaction TMC is a subsidiary that produces and sells marble products with the granted concessions of a limestone quarry and marble quarry. TMC employed the Company for the limestone quarry management according to the concession certificate no.32517 and signed the KFS agreement with the Company to supply the kiln feed stone in the long-term starting from 1 June 2020. The stone's prices are based on the L-Size and S-Size according to the conditions in the agreement and the selling price as prescribed in the pricing policy (based on the market price or as agreed). | 2025-12-31T00:00 |
| Golden Lime Engineering Company Limited (“GLE”) Subsidiary Company | Juristic Person | Engineering Design | Service Agreement –Other service - Short-term loan - Subsidiaries Company - 100% shareholding by the Company - Service Agreement –Other service - Short-term loan Necessity entering a connected transaction The Service Agreement through which certain services provide by GLE that more specifically specialized in providing engineer design services and supporting know-how of the EOD lime kiln with the commissioning work until the production to the running process. Including the project to improving the production process and installation machine and equipment. The Company will clearly benefit from improvements to its Engineering Design, Technical Process Service and Support of EOD lime kiln running of the production process at Huay Pa Wai Plant through this Service Agreement, the Company’s will be further received the engineering support better in its Engineering Design, technical and operational challenges. On the date of 9 November 2017, the Company’s Board of Directors no.5/2017 has resolved to approve the transaction | 2025-12-31T00:00 |
| Maxwin Builders Company Limited | Juristic Person | Provides construction home and building services." | Sale and Service -Co-shareholder (indirect) Necessity entering a connected transaction Maxwin Builders provides construction services for homes and buildings, including the procurement and installation of marble products from its subsidiary, Thai Marble Corp., Ltd. This transaction was conducted under general commercial terms,consistent with normal business practices, similar to other customers | 2025-12-31T00:00 |
| Premthai Energy Company Limited (“PTE”) | Juristic Person | Energy , Fuel limestone, dolomite Procurement | Product Purchase / Engineering Service – Related Party -Co-shareholder (indirect) Necessity entering a connected transaction The Board of Directors’ Meeting no.2/2019 held on 3 April 2019 approved to sign a Service Agreement related to the procurement of raw materials, limestone, dolomite, and solid fuel, this Service Agreement is from 1 January 2019 - Other connected transaction was in which PTE to sell the coal for Saraburi Quick lime Co., Ltd. (Subsidiary Company), in accordance with terms and conditions of the procurement of the coal energy by comparing the prices with other Supplier or Traders of Coal companies. -The Board of Directors' meeting No. 2/2023 resolved to approve a transaction with a related party , Premthai Energy Company Limited, a juristic person sharing directors, in purchasing coal (Indonesia Steam Coal) in the amount of 20,000 ton with as same conditions as other juristic persons by comparing prices and conditions according to the price criteria and market conditions -Other transaction, PEL enters to the transaction of the engineering service with GLE. Service Agreements-Related Party -Co-shareholder (indirect) Necessity entering a connected transaction Under the Service Agreement, PEL service was to employ senior geologists and international solid fuel commodity experts who shall provide services supporting geological assessment of limestone/dolomite deposits (a prime raw material), procurement, contract negotiations with suppliers, monitoring and controlling stocks including the analysis to evaluate the amount of raw materials needed for production. Procurement of solid fuels such as petcoke, monitoring international supply and demand of petcoke market in USA, Europe and Asia, comparing sources of the Petcoke in terms of quality / cost / logistics, survey and provide appropriate marine and road transportation services. Apart from the aforementioned service agreements, there was also the scope of service that was a regular operation in the Company's business. By being a service provider jetty for loading fuel, raw material and product including transfer services, weighing scale through at the jetty, Warehouse Renting for fuel storage/Product/Raw material during transfer or delivery from the port of origin to the port of destination or sent to the factory or Koh Sichang, which was the service offering in the same conditions as the regular business service with the price according to the agreed quotation. | 2025-12-31T00:00 |
| Premthai Logistics Company Limited (“PTL”) | Juristic Person | Logistics Jetty and transportation | Transportation - the Related Party -Co-shareholder (indirect) Necessity entering a connected transaction This transaction is a connected transaction in which PTL transports and delivers the Company’s products to customers. This transaction was conducted in accordance with terms and conditions of the procurement of general contractor for transportation by comparing the prices with other contractors of transportation companies. | 2025-12-31T00:00 |
| Carmeuse Majan LLC (“CMMJ”) | Juristic Person | Lime Industry | Product Purchase Relation -Co-shareholder (indirect) / Co-directors - Carmeuse Majan, located in Oman's Salalah Free Zone, is a joint venture operated by affiliated companies of the Carmeuse Group, the GP Group and certain other local shareholders. - There are common indirect shareholders, which is Carmeuse Holding SA, and common directors. Necessity entering a connected transaction The Company occasionally needs lime as product for hydration and milling processes, to produce blends for certain customers, as well as quantity supplements to its own production in the peak periods of the sugar season when demand for milled and hydrated lime is occasionally above production capacity. The lime from Carmeuse Majan LLC has quality that is higher than that was available from any domestic vendor, yet the purchase price was the same or even below of domestic lime as raw material purchases in the same period. The reuse of the plastic bags in which the lime from Carmeuse Majan is delivered offers further cost advantages. The Board of Directors Meeting No.6/2016 held on November 11, 2016, authorized the management of the Company to enter into a raw material purchase agreement for burnt lime with Carmeuse Majan LLC (SFZ) at a price that is below of other comparable foreign vendors. The Audit Committee in its meeting No.4/2016 held on 11 November 2016 suggested that the Company should compare the price from other domestic offering at the same time as well. The comparison showed that the price offered by domestic suppliers is comparable, but for a lower quality, while the alternative foreign suppliers offer both higher price and a lower quality. Also, the transaction provided an additional layer of supply security to the customers of the Company in the sugar peak periods of December 2016 and January 2017 And for the purchasing during the year 2017 to support production to produce quicklime powder and hydrated lime when the kiln to shut down to maintenance and the lump lime from kiln do not enough to delivery to the contract customer. | 2025-12-31T00:00 |
| TEC for LIME (“TFL”) | Juristic Person | Technical and Services Consultant | Purchase Raw Material / Account Payable Relation -Co-shareholder (indirect) - Related Party For Service fee for a consultant -Tech for Lime (TFL) is a Carmeuse Group affiliate company -There are common indirect shareholders Necessity entering a connected transaction on the date of 11 November 2016, the Company’s Board of Directors no. 6/2016 has resolved to approve that the Company enters into a Service Agreement. This Service Agreement is scheduled to be signed before 30 November 2016. The Service Agreement will enter into effect on 1 January 2017 for an indefinite duration. Either Party may however terminate this Agreement at any time, without cause, upon three (3) months’ written prior notice to the other Party. The Board of Directors’ Meeting no.1/2019 which held on 26 February 2019 decided to approve an adjustment of the service rates. Therefore, the Company’s Board of Directors’ Meeting no.2/2019 which held on 3 April 2019 has approved to sign a new Service Agreement with updated rates effective since 1 April 2019. (Updated) This transaction is a connected transaction through which certain services will be provided by CRT or TFL to the Company. CRT or TFL is more specifically specialized in providing technical services, support and know-how covering areas such as geology, mining, engineering, production, logistics, process automation etc to the various companies within the Carmeuse Group. Through the Service Agreement, CRT or TFL will extend the benefit of these services to the Company in support of the development and be streamlining of the Company’s business and processes. The Company will clearly benefit from improvements to its Engineering Process, Technical Process, Lime Stone Sourcing process, Automation and Quality Management process. Through this Service Agreement, the Company’s technical employees will be further trained so as to support the Company better in its technical and operational challenges. As a member of the Carmeuse Group, CRT or TFL is bringing know-how and support of a lime player with 155 years of experience in a large number of working environments. | 2025-12-31T00:00 |
| Christiani & Nielsen Energy Solutions (“CNES”) | Juristic Person | the subsidiary of Christiani & Niesen (Thailand) Public Company Limited (“CNT”) Energy, Solar Procurement and Engineering and Installation Services | Consulting Fee -Co-shareholder (indirect) Necessity entering a connected transaction -The Board of Directors’ Meeting no.3/2019 held on 14 May 2019 approved the Company to sign of the Letter of Intent (“LOI”) / Memorandum of Understanding (“MOU”) of the service agreement for the Solar Farm Project. Under the terms of the LOI, CNES will provide services related to the design, shortlisting and selection of suppliers and the obtaining of the necessary approvals and services related to the erection of a Solar Farm with a 2-2.5 MW capacity. CNES had submitted the best techno-commercial offer for the 2MW Solar Farm Project. And L.O.I condition signing, the realization of the Solar Farm Project is dependent upon the successful receipt of the following conditions - BOI privileges - Credit facility from a financial institution - All other permits necessary to build and operate the Solar Farm to produce electricity . The value of the related transaction included the difference from the value that the service provider can negotiate with the equipment supplier according to the project, which is the part received after working within the scope of the contract.Additionally, the Board of Directors’ Meeting no.4/2021 of Golden Lime (Plc.), (‘the Company’) held on 11 August 2021 approved another connected transaction to the Solar Farm 0.5 MW capacity expansion project which relatively was classified as connected transaction under “assets or service” transaction of more than1 million baht but less than 20 million baht | 2025-12-31T00:00 |
| Carmeuse Research & Technology SA (“CM SA”) | Juristic Person | CM SA conducts research and experimental development in natural sciences and engineering, providing professional engineering and technological development services for Carmeuse group | Consulting Fee / Software Services Fees - Co-shareholder (indirect) Necessity entering a connected transaction -CM SA disposes of a specialized laboratory which performs from time-to-time various quality tests on the limestone used by Golden Lime in its production process. The tests are performed based upon pre-defined laboratory services rates. The Carmeuse Group has a policy to promote technology and digital development to enhance business competitiveness. Under the management of Carmeuse EMEA, SUTHA has developed and integrated its IT network through Carmeuse’s IT infrastructure, including the use of standardized software and network services within the Group. In August 2023, management shared details on investments, system expenses, and market prices with both the Audit Committee and the Board of Directors. The installation was finished in 2024, and software fees—calculated according to real user activity—will be billed for the first time in 2025. | 2025-12-31T00:00 |
| CARMEUSE Coordination Center S.A. (“CCC”) | Juristic Person | A management group company of Carmeuse | Consulting Fee -Co-shareholder (indirect) Necessity entering a connected transaction CCC will provide internal audit services to the company by sending a team of experts with knowledge in the company's business operations. This service agreement was approved by the Board of Directors' Meeting No. 1/2020 on February 25, 2020. The Audit Committee and the Board of Directors, excluding interested directors, jointly considered the related transaction and agreed that it is appropriate and beneficial to the company. The company will benefit from internal control system audits conducted by experienced and knowledgeable internal auditors from the Carmeuse Group, which has over 160 years of expertise and an understanding of the competitive nature of the business. The service fee charged by CCC is considered reasonable compared to other internal control audit service providers | 2025-12-31T00:00 |
| Directors/Key management personnel | Person | Remuneration for Executives and Directors - To be directors and executives of the Company Necessity entering a connected transaction The remuneration and benefit of the executives and directors of the Company in the short-term and long-term. | 2025-12-31T00:00 |
Transactions by Counterparty
| Transactions |
|---|
| 0.0 · Necessity: As specified in the TMC details. · Description: Seperate Financial Statement · As of yesteryear: 0.0 · Nature of transaction: Other income -Transportation · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.07 · 5.52 · Necessity: As specified in the GLE details. · Description: Seperate Financial Statement · As of yesteryear: 3.0 · Nature of transaction: Other Income - Services · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 3.0 · 100.98 · Necessity: As specified in the GLE details. · Description: Seperate Financial Statement · As of yesteryear: 112.07 · Nature of transaction: Purchase of Goods/Raw material · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 107.42 · 0.0 · Necessity: It is a subsidiary, and the interest rates are set according to the terms and conditions At the rate 2.50% per year · Description: Seperate Financial Statement · As of yesteryear: 0.0 · Nature of transaction: Interest expense · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.12 · 2.87 · Necessity: The balances of the Account between company and those Subsidiary company as of 31 December · Description: Seperate Financial Statement · As of yesteryear: 1.62 · Nature of transaction: Trade and other receivables-Subsidiaries · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 1.6 · 45.48 · Necessity: The balances of the Account between company and those Subsidiary company as of 31 December · Description: Seperate Financial Statement · As of yesteryear: 37.54 · Nature of transaction: Trade and Payables-Subsidiaries · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 27.35 |
| 0.0 · Necessity: Accounting and related service fees. At the rate specified in the agreement As specified in the GLE details · Description: Seperate Financial Statement · As of yesteryear: 0.48 · Nature of transaction: Other income-Services · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 1.44 · 0.36 · Necessity: Provide loan for subsidiary company At the rate 2.00% per year · Description: Seperate Financial Statement · As of yesteryear: 0.4 · Nature of transaction: Interest income · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.38 · 0.0 · Necessity: Providing engineering project services At the rate specified in the agreement As specified in the GLE details · Description: Seperate Financial Statement · As of yesteryear: 0.1 · Nature of transaction: Consulting Fees (Engineering) · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.16 · 0.0 · Necessity: It is an asset from an investment project assigned to GLE for execution. At the rate specified in the agreement · Description: Seperate Financial Statement · As of yesteryear: 11.35 · Nature of transaction: Consulting Fees (Buy Asset) As specified in the GLE details · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 42.71 · 4.1 · Necessity: The balances of the Account between company and those subsidiary · Description: Seperate Financial Statement · As of yesteryear: 2.48 · Nature of transaction: Trade and other receivables-Subsidiaries · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.18 · 0.0 · Necessity: The balances of the Account between company and those subsidiary · Description: Seperate Financial Statement · As of yesteryear: 0.0 · Nature of transaction: Other nOther non-current asset-Subsidiarieson-current asset-Subsidiaries As specified in the GLE details · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 3.27 · 0.0 · Necessity: The balances of the Account between company and those subsidiary · Description: Seperate Financial Statement · As of yesteryear: 4.54 · Nature of transaction: Trade and Payables-Subsidiaries · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 5.0 · 16.0 · Necessity: The balances of the Account between company and those subsidiary · Description: Seperate Financial Statement · As of yesteryear: 24.5 · Nature of transaction: Short-term loan to subsidiary · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 13.5 |
| 0.03 · Necessity: This involves the sale and installation of marble, carried out by Thai Marble Corp., Ltd., a subsidiary At the agreed price As specified in the Mexwin details. · Description: Consolidated · As of yesteryear: 3.2 · Nature of transaction: Sale and Service · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.0 · 0.38 · Necessity: The balances of the Account between company and those related companies period ended 31 December · Description: Consolidated · As of yesteryear: 1.8 · Nature of transaction: Trade and other receivables-related Companies · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.0 |
| 41.94 · Necessity: -As specified in the PTE details. · Description: Consolidated and Seperate Financial Statement · As of yesteryear: 0.0 · Nature of transaction: Purchase of Goods/Raw material · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 127.73 · 0.6 · Necessity: As specified in the PTE details · Description: Consolidated and Seperate Financial Statement · As of yesteryear: 0.6 · Nature of transaction: Cost of raw material procurement · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed the transaction · As of year before yesteryear: 0.6 · 2.08 · Necessity: As specified in the PTE details. · Description: Consolidated and Seperate Financial Statement · As of yesteryear: 0.11 · Nature of transaction: Other current liabilities-related Companies · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 7.26 |
| 0.0 · Necessity: It is a purchase of goods and raw materials for the production process At the agreed price As specified in the PTL details · Description: Consolidated and Seperate financial statement · As of yesteryear: 25.6 · Nature of transaction: Purchase of Goods/Raw material · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 21.36 · 1.14 · Necessity: Translportation Expeses At the agreed price As specified in the PTL details · Description: Consolidated and Seperate financial statement · As of yesteryear: 4.2 · Nature of transaction: Transportation expenses · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 4.98 · 5.72 · Necessity: The balances of the Account between company and those related companies period ended 31 December · Description: Consolidated and Seperate financial statement · As of yesteryear: 3.68 · Nature of transaction: Other current liabilities-related Companies · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 3.55 |
| 0.0 · Necessity: These are consultancy fees paid based on actual work performed and expenses incurred, or reimbursements for speaker fees for conducted training sessions -As specified in the CM Majan details. · Description: Consolidated and Seperate financial statement · As of yesteryear: 0.17 · Nature of transaction: Purchase of Goods/Raw material at the agreed price · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.28 · 0.0 · Necessity: The balances of the Account between company and those related companies period ended 31 December · Description: Consolidated and Seperate financial statement · As of yesteryear: 0.17 · Nature of transaction: Other current liabilities-related Companies · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.0 |
| 0.0 · Necessity: Consultant Fees At the rate specified in the agreement As specified in the TFL details. · Description: Consolidated and Seperate financial statement · As of yesteryear: 0.11 · Nature of transaction: Consulting Fee · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.76 · 0.27 · Necessity: At the rate specified in the agreement · Description: Consolidated and Seperate financial statement · As of yesteryear: 0.24 · Nature of transaction: Consulting Fee (CAVA) As specified in the TFL details. · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.22 · 0.02 · Necessity: The balances of the Account between company and those related companies period ended 31 December · Description: Consolidated and Seperate financial statement · As of yesteryear: 0.03 · Nature of transaction: Other current liabilities-related Companies · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.03 |
| 0.0 · Necessity: As specified in the CNES details. · Description: Consolidated and Seperate financial statement · As of yesteryear: 0.0 · Nature of transaction: Consulting Fee (Asset) · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 10.66 · 1.38 · Necessity: The balances of the Account between company and those related companies period ended 31 December · Description: Consolidated and Seperate financial statement · As of yesteryear: 1.34 · Nature of transaction: Other current liabilities-related Companies · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 1.34 |
| 5.64 · Necessity: This charge is based on the number of users who are connected through the Carmeuse Group’s network, as presented in the package to the Board of Directors in August 2023, and it also includes the IT Management Fees. · Description: Consolidated and Seperate financial statement · As of yesteryear: 0.0 · Nature of transaction: Software Services Fees · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.04 · 5.68 · Necessity: The balances of the Account between company and those related companies period ended 31 December · Description: Consolidated and Seperate financial statement · As of yesteryear: 0.0 · Nature of transaction: Other current liabilities-related Companies · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.0 |
| 0.0 · Necessity: As specified in the contract rate As specified in the CCC details · Description: Consolidated and Seperate financial statement · As of yesteryear: 1.03 · Nature of transaction: Consulting Fee (Internal audit) · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.0 · 0.0 · Necessity: The balances of the Account between company and those related companies period ended 31 December As specified in the CCC details · Description: Consolidated and Seperate financial statement · As of yesteryear: 1.03 · Nature of transaction: Other current liabilities-related Companies · Audit committee opinion: It is deemed appropriate to propose to the board meeting for approval to proceed with the transaction · As of year before yesteryear: 0.0 |
| 62.76 · Necessity: Consolidated · Description: Short term benefit · As of yesteryear: 56.28 · Nature of transaction: Directors and Executives Remuneration · Audit committee opinion: The disclosure on the Directors and Key management Remuneration · As of year before yesteryear: 51.72 · 1.85 · Necessity: Consolidated · Description: Post-employee benefits of directors and key management · As of yesteryear: 1.46 · Nature of transaction: Post-employee benefits · Audit committee opinion: The disclosure on the Directors and Key management Remuneration · As of year before yesteryear: 1.43 · 0.0 · Necessity: Financial Statement · Description: Rental Income · Nature of transaction: Trade and other receivables-related transaction · Audit committee opinion: Related transaction Disclosure · 0.1 · Necessity: Related transaction_Directors and Execuitives(Expenses) · Description: Related transaction Disclosure · Nature of transaction: Other curent liabilities-related transaction · Audit committee opinion: This item is recorded under the Mobile Expenses system as an outstanding payment |
Policy & Future Trends
Policy, Measures & Approval Process
Preventing conflicts of interest
A director and an executive will file with the company a report on his interest or a related person's interest in relation to management of the company or the subsidiary for the Company to have information to comply with provisions concerning with the connected transactions, by which conflicts of interest may arise and result in a transfer of interest of the Company and the subsidiary. Furthermore, the director and executive have below fiduciary duties to conduct themselves and make decisions without any direct or indirect interest
A director and an executive will file with the company a report on his interest or a related person's interest in relation to management of the company or the subsidiary in accordance with the rules, conditions and procedures as specified in the notification of the Capital Market Supervisory Board.( Section 89/14 of the Securities and Exchange Act stipulates that)
A company secretary will submit a copy of report on interest under Section 89/14 to the Chairman and the Chairman of audit committee within seven business days from the date on which the company has received such report. (Section 89/16 of the Securities and Exchange Act)
The board of directors is to establish details on the rules, conditions and procedures for reporting the conflict of interest by the director, executive and related person, in order to comply with Section 89/14, and disclose via the website of the Company. (Notification of the Capital Market Supervisory Board No. TorChor. 2/2552)
Section 88 of the Public Limited Company Act B.E. 2535 stipulates that a director will notify the company without delay in the following cases:
A. having a direct or indirect interest in any contract which is made by the company during an accounting year, and will indicate the nature of the contract, names of the contracting party and interest of the director in the contract (if any);
B. holding shares or debentures of the company or an affiliated company and will indicate the total number of shares increasing or decreasing during an accounting year (if any).
The Board of Directors has approved the policy and procedures for related party transactions. Therefore, the transactions with related individual person or juristic person which may have a potential conflict are done transparently and such that the interests of the Company are protected. The policy is summarized as follows:
Preventing conflicts of interest
Principle
The Board of Directors has resolved to establish policies and procedures in conducting related party transactions to ensure that all actions are legal and ethical and do not compromise shareholder value.
Guidelines
1) Director, executives and employees should avoid any action that against the interests of the company, either in the from contacts with your company's trade partners, such as partners, customers, competitors, or from using opportunities or information gained from being a director, or employees in their own interests, and doing business that competes with the company, or doing other work than the work of the company This has a detrimental effect on function on duty.
2) Directors, executives, and employees shall refrain from holding shares in the Company's competitors. In the case where an employee has acquired shares prior to employment, or before the company goes into business, or acquired by way of inheritance employees must report to the Company via hierarchical bosses.
3) No Director shall ,either for his/her own benefit or the benefit of others, operate any business which has the same nature as and is in competition with the business of the Company or become a partner in an ordinary partnership or become a partner with unlimited liability in any limited partnership or become a director of any limited company or public limited companies which has the same nature and is in competition with the business of the Company, unless he or she has notified to the shareholders meeting prior to the resolution for his or her appointment.
4) The Directors, Management and Employees shall not, for their own personal gains, receive any money or benefit from customers, or other benefits from other persons with duties or business related to the Company unless on traditional occasions or festivals’ standard practices.
5) The company has no policy in providing financial assistance, guarantees to individuals, executives, or companies that are not subsidiaries.
6) Personnel under employment contract should not spend office hours in doing any work for personal benefit resulting in neglect of duties and insufficient work time to carry out duties according to the scope of duties completely.
Future Trends in Related Party Transactions
Transactions between the Company and any of its directors, executives, or other related persons shall be approved by a shareholder's meeting, unless such transactions involve a trade agreement in the manner that an ordinary person shall generally make with his contractual party in the same situation with the trade negotiation power that he has from the position of director, executive, or related person, as the case may be, and is a trade agreement that is approved by the Board of Directors or conforms to the principles previously approved by the Board of Directors.
In order to approve the related party transaction between the Company and person who may have a conflict of interest or holding a stake in the Company, the Audit Committee will provide counsel regarding the necessity for the transaction and appropriateness in terms of the price of the transaction, taking into consideration various conditions to ensure the conformity to the ordinary course of business in the industry, and the Audit Committee will compare the price with a third party's price or the market price. If the Audit Committee does not have any expertise to consider the transaction that may occur, the Company shall provide persons who have knowledge and expertise, such as an auditor, appraiser, or law firm, which is independent from the Company and the person who may have a conflict of interest to provide consultancy on such related party transactions, which shall be used to supplement the consideration of the Audit Committee for their proposal to the meeting of the Board of Directors or shareholders, as the case may be; in which case, the director who holds the interest shall not have the right to vote on the transaction. In addition, there will be a disclosure of related party transactions in the Notes to Financial Statements that are examined or audited by the Company's auditor. The Board of Directors of the Company shall take care of the matter to ensure the conformity to the laws on securities and securities exchanges, regulations, announcements, orders, or the requirements of the Capital Market Supervisory Board and the Stock Exchange of Thailand and shall observe the requirements regarding the disclosure of connected transactions and the acquisition or distribution of major assets of the Company, or its subsidiaries, as well as the accounting principles specified by the Federation of Accounting and Certified Public Accountant of Thailand.
To enter into the transactions with subsidiaries or the connected parties, the pricing policy is on the Arm’s Length Principal basis means on a market price basis or on the agreed price as same as with other business partners and the pricing policy is regularly updated and review before approval by the Board. The general related transactions were detailed and disclosed in the report of internal control and connected transactions with connected parties according to the Notification of the Capital Market Supervisory Office No. Tor Chor. 21/2551 Re: Rules on Related Transactions of Listed Company. The company has prepared information in compliance with the criteria and requirements and disclosed it to the Stock Exchange of Thailand strictly.
Appraised Assets & Appraisal Prices
Appraised Assets & Appraisal Prices — Introduction
There were no significant related party asset acquisitions or conflicts of interest in 2024.